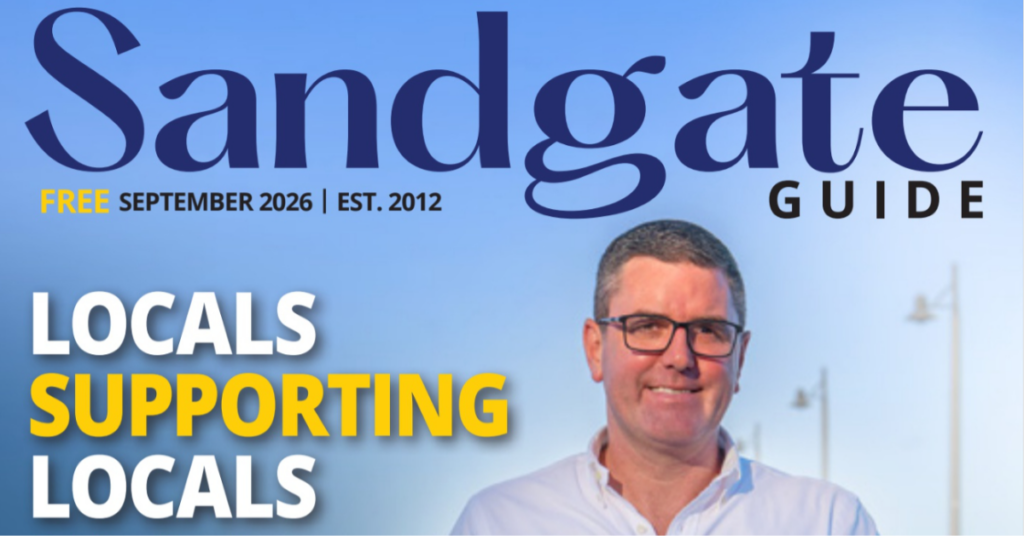
The Sandgate Guide recently featured PierPoint Lending’s Adam Bailey as the cover story of its September 2026 issue, celebrating the role local business owners play in the community (read the full story at sandgateguide.com.au). It’s a reminder of something we believe strongly at PierPoint Lending: being part of a community isn’t just good citizenship, it’s good practice. For a mortgage broker, local knowledge does more than build goodwill. It directly shapes the quality of advice a client receives, from how a property is assessed to how a loan is structured.
A mortgage broker’s job is to match a client’s circumstances with the right lending solution, but the “right” solution often depends on local context that a generic, one-size-fits-all approach can miss. Brokers who understand a specific area, its property values, its growth trends, its flood and zoning considerations, and the lenders who are actively competing for business there, can identify risks and opportunities that a purely numbers-based assessment would overlook. For clients, this can mean a smoother valuation process, access to more suitable lenders, better preparation for local council or insurance requirements, and lending strategies built around where they actually live and buy, not a national average. Community involvement, of the kind Adam brings to local events and schools around Sandgate, is often the visible sign of a broker who has taken the time to fully understand the area they serve.
What “Local Knowledge” Actually Means for a Broker
Local knowledge isn’t just knowing a suburb’s name and postcode. For a mortgage broker, it typically includes:
- Recent sale prices and how they compare to a bank’s own valuation models
- Which streets or pockets are prone to flooding, bushfire risk, or other insurance-affecting factors
- Zoning and development activity that could affect future property values
- The mix of housing stock (units, character homes, new builds) and how lenders view each
- Local employment trends and industries that influence a client’s income stability
- Which lenders are actively competitive in that market, and which are pulling back
How Local Knowledge Benefits Bayside Clients
More Accurate Property Assessments
Bank valuations don’t always reflect what’s actually happening on the ground. Sandgate and Brighton, for example, sit at the mouth of Bramble Bay, so their flood exposure is driven mainly by king tides and storm surge, which is a different risk profile to the riverine flooding that has affected many of Brisbane’s southern, river-adjacent suburbs during major events such as the 2011 and 2022 floods. A lender or valuer unfamiliar with that distinction can apply a generic “flood risk” assessment to a bayside property that doesn’t reflect its actual overlay category or insurance implications. A broker who understands the difference can put the right context in front of a lender, rather than letting an overly cautious, blanket assessment affect the outcome.
The same applies to pricing. A broker who knows that a particular Sandgate or Brighton pocket has seen strong recent demand, or that a certain style of character home is undervalued by standard valuation models, can push back on a low valuation with evidence, rather than simply accepting the bank’s figure.
Better-Matched Lenders
Not every lender treats every postcode, or every property type, the same way. Some are more comfortable lending on older Queenslanders, units in older buildings, or properties in flood-affected zones, while others apply stricter conditions. Knowing which lenders are competitive in the bayside market saves clients from wasted applications and unnecessary delays.
Realistic Guidance for First Home Buyers and Growing Families
First home buyers in particular benefit from a broker who understands local price points and typical borrowing patterns. Rather than generic advice, clients get a clear sense of what’s achievable in their target suburb, what to budget for beyond the loan itself (such as body corporate fees or older-home maintenance), and how their circumstances compare to others making similar moves in the same area.
Stronger Relationships with Local Referral Partners
Being active in the community, whether through schools, sporting clubs, or local events, naturally builds relationships with local real estate agents, conveyancers, and accountants. For clients, this often means a more coordinated experience, with fewer delays caused by parties who don’t know or trust each other.
A Broker Who Is Genuinely Invested in the Outcome
There is a difference between a broker who processes an application and one who has a personal stake in the community their clients are buying into. That difference tends to show up in the level of care taken, the willingness to go back to a lender and negotiate, and the ongoing support provided after settlement.
Being part of a community, and taking the time to understand it properly, shapes the kind of advice a broker can offer. It’s part of why Adam has always seen PierPoint Lending’s work in Sandgate as more than transactional. If you’d like to talk through your own situation with someone who knows the local market, get in touch with PierPoint Lending today.
Frequently Asked Questions
Does a local mortgage broker only work with local lenders?
No. A broker with local knowledge still compares options across a wide panel of lenders, often dozens, both local and national. The advantage of local knowledge isn’t a narrower lender panel, it’s a better-informed comparison, because the broker understands how each lender is likely to view a particular property or area.
Will using a local broker cost more than going directly to a bank?
Typically, no. Mortgage brokers are usually paid a commission by the lender once a loan settles, not a fee charged directly to the client. This means clients can access broader lender comparisons and local market insight at no direct cost in most cases.
Can local knowledge really affect whether a loan is approved?
Yes, in some cases. If a lender’s valuation comes in lower than expected, or a property has features that make some lenders cautious (such as flood overlay, small floor size, or unusual zoning), a broker who understands the local market and the specific lender policies can often find an alternative solution, or provide the evidence needed to challenge an inaccurate valuation.
Why does community involvement matter if I just need a home loan?
Community involvement itself doesn’t secure a better rate, but it’s usually a sign that your broker has taken the time to fully understand the area, its property market, and the people in it, rather than treating every client as a generic transaction.
Is local knowledge only useful for buying, or does it help with refinancing too?
It helps with both. Understanding local property values and lender appetite is just as relevant when refinancing, particularly if a client’s property has increased in value or if their circumstances have changed since their original loan was approved.
Enquire Now
Complete the enquiry below and a member of the PierPoint Lending team will contact you to schedule a complimentary home loan review.